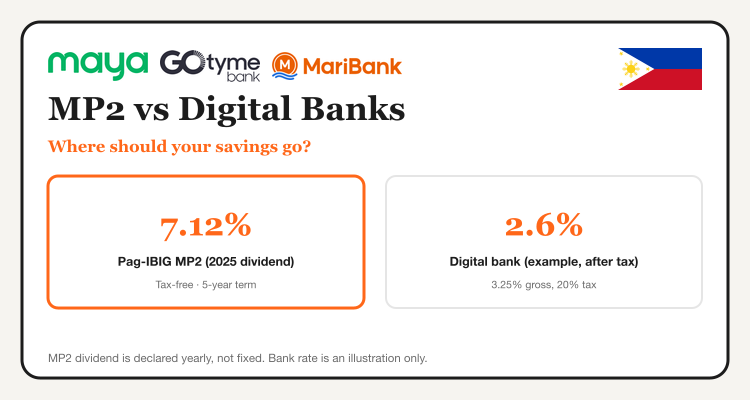
MP2 vs Digital Banks in One Table
| Feature | Pag-IBIG MP2 | Digital bank savings |
|---|---|---|
| Latest rate | 7.12% dividend for 2025 | About 2.3% to 3.25% gross, varies |
| Tax | Dividends are tax-free | 20% final tax on interest |
| Term | 5 years, then payout | No lock-in |
| Minimum | ₱500 | Often low or none |
| Protection | Backed through the Pag-IBIG Fund | PDIC up to ₱1 million per bank |
| Best for | Money you will not touch | Emergency fund and daily cash |
The MP2 rate comes from Pag-IBIG's announcement of a record ₱64.34 billion in total dividends for 2025, with Regular Savings at 6.62%. Digital bank rates vary and often promo-based, so the bank figure above is a range, not a promise.
A ₱100,000 Example
Say you save ₱100,000 for one year. At MP2's 7.12%, the dividend is ₱7,120. At a 3.25% digital bank rate, the interest is ₱3,250 before tax, and ₱2,600 after the 20% tax. The gap is ₱4,520 a year on the same amount.
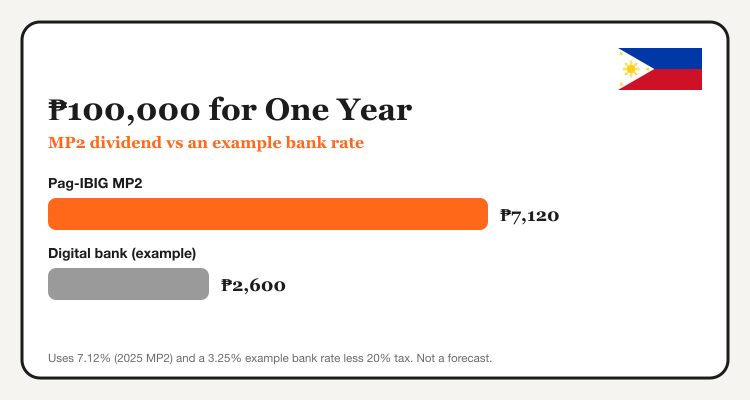
This is an illustration, not a forecast. MP2 pays at the end of the term, and the dividend changes each year. A promo bank rate can also end any time.
Why the Rates Differ
MP2 is a government-run savings program, and Pag-IBIG Fund invests members' contributions and shares the earnings as dividends. A bank pays interest from lending and operations, and cuts it when central bank rates fall. That is why MP2 dividends can sit far above savings rates, and why they are not fixed.
So the 7.12% is real money, but it comes with a commitment. Decide how long you can leave the cash alone before you decide where it goes.
Where MP2 Hurts
Liquidity is the trade-off. MP2 is a 5-year savings product, and leaving early can cost you part of the dividends. If a job loss or a medical bill hits in year two, that lock-in matters. Our MP2 savings guide explains early withdrawal in detail.
Where Digital Banks Win
Digital banks give you your money back the same day. Deposits are covered by PDIC up to ₱1 million, and many have no minimum balance. Maya, GoTyme and MariBank all let you open an account from your phone.
MariBank also runs a Christmas campaign for new users, with total potential rewards of up to ₱700, terms apply. Read the MariBank Christmas campaign guide, then sign up with code MBTIPIDNATION.
Keep 3 to 6 months of expenses somewhere you can reach it today.
Which One Fits You
| Your situation | Better fit |
|---|---|
| Need cash within a year | Digital bank |
| Saving for a goal 5 years away | MP2 |
| Building an emergency fund | Digital bank |
| Active Pag-IBIG member with spare cash | MP2 |
| Not sure yet | Split: bank first, MP2 second |
Common Mistakes
- Putting an emergency fund into MP2, then cashing out early.
- Comparing a gross bank rate with a tax-free MP2 rate. Subtract the 20% tax first.
- Chasing a promo rate without checking when it ends.
- Assuming 7.12% repeats every year. The dividend is declared annually.
This is general information, not personalized financial advice. Most Filipinos do better by doing both, with a clear job for each peso. Write down what each account is for, and the choice gets easier.
A Simple Split That Works
- Build the emergency fund first. Put 3 to 6 months of expenses in a digital bank.
- Open MP2 with the extra. Add a fixed amount monthly, even ₱500.
- Never use MP2 money for bills. Treat it as untouchable for 5 years.
- Review every February. Check the declared dividend and adjust.
If you want to compare more digital banks, see best digital banks in the Philippines. Thinking about bonds too? Read GBonds and Retail Treasury Bonds.
See which app fits your daily banking before you move money.