Quick Facts
💰 Credit limit: ₱2,500 to ₱100,000
📊 Monthly add-on rate: 0.95% to 2.95%, based on approval
📅 Terms: 3, 6, or 12 months
🚫 No processing fee, no collateral, no guarantor required
🔒 Access: Invite-only, pre-qualified MariBank customers only
What Is Mari Loan?
Mari Loan, formerly called MariBank Credit, is an unsecured revolving credit line tied to your MariBank deposit account. Once approved, you get a credit limit and can withdraw any amount between ₱1,000 and that limit straight into your MariBank savings account, as many times as you need, as long as your total outstanding balance stays within the approved limit. Your limit restores once a loan is fully repaid, so it works closer to a standing credit facility than a one-time loan.
Each withdrawal lets you pick a repayment term of 3, 6, or 12 months, and the monthly installment is deducted automatically from your MariBank Savings Account, so there's no manual payment step as long as your balance covers it. Application is currently limited to pre-qualified customers inside the MariBank app, there's no open application form on the website for new users to request access.
Mari Loan Interest Rates & Fees
MariBank's own Product Disclosure Sheet (PDS) lists a range rather than one flat rate, your actual rate depends on MariBank's credit evaluation of your profile.
| Fee Type | Amount |
|---|---|
| Monthly Add-on Interest Rate | 0.95% – 2.95% |
| Monthly Contractual Rate (3-month term) | 1.42% – 4.36% |
| Monthly Contractual Rate (6-month term) | 1.61% – 4.86% |
| Monthly Contractual Rate (12-month term) | 1.70% – 5.00% |
| Documentary Stamp Tax (DST) | 0.75% × Loan Amount × (Loan Tenure in Days ÷ 365), deducted from disbursement |
| Late Penalty Interest | 0.17% per day on overdue principal |
| Prepayment Fee | 3% of outstanding principal + unpaid remaining interest, or ₱300, whichever is higher (effective since January 15, 2025) |
| Processing / Activation Fee | None |
Figures sourced directly from MariBank's official Mari Loan Product Disclosure Sheet. Rates are subject to MariBank's approval and may change, always confirm the current PDS in-app before accepting a loan offer.
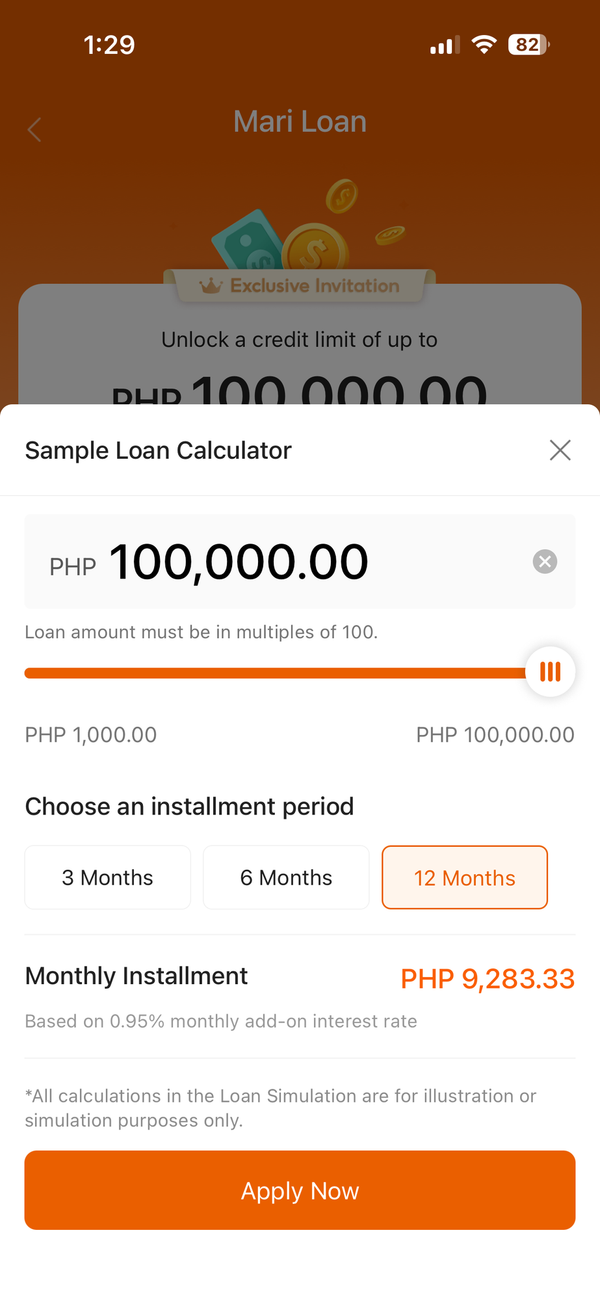
MariBank's own formula for your monthly installment is: (Approved Amount × Fixed Monthly Add-on Rate × Tenure in Months + Approved Amount) ÷ Tenure in Months. That's the same flat add-on structure most Philippine banks use for personal loans, interest is calculated once on the full original amount, not on a shrinking balance, which is why the Monthly Contractual Rate (the true cost once spread evenly) runs noticeably higher than the headline add-on rate.
Mari Loan Calculator
Estimate your monthly payment using MariBank's own add-on rate formula. Adjust the amount, rate, and term to match your situation, this is for illustration only, your actual approved rate and total cost depend on MariBank's credit evaluation.
Estimate only, based on MariBank's published add-on rate formula. Excludes Documentary Stamp Tax (0.75% of loan amount) deducted from disbursement. Confirm the exact figures in the MariBank app's own Sample Loan Calculator before applying.
How to Apply for Mari Loan
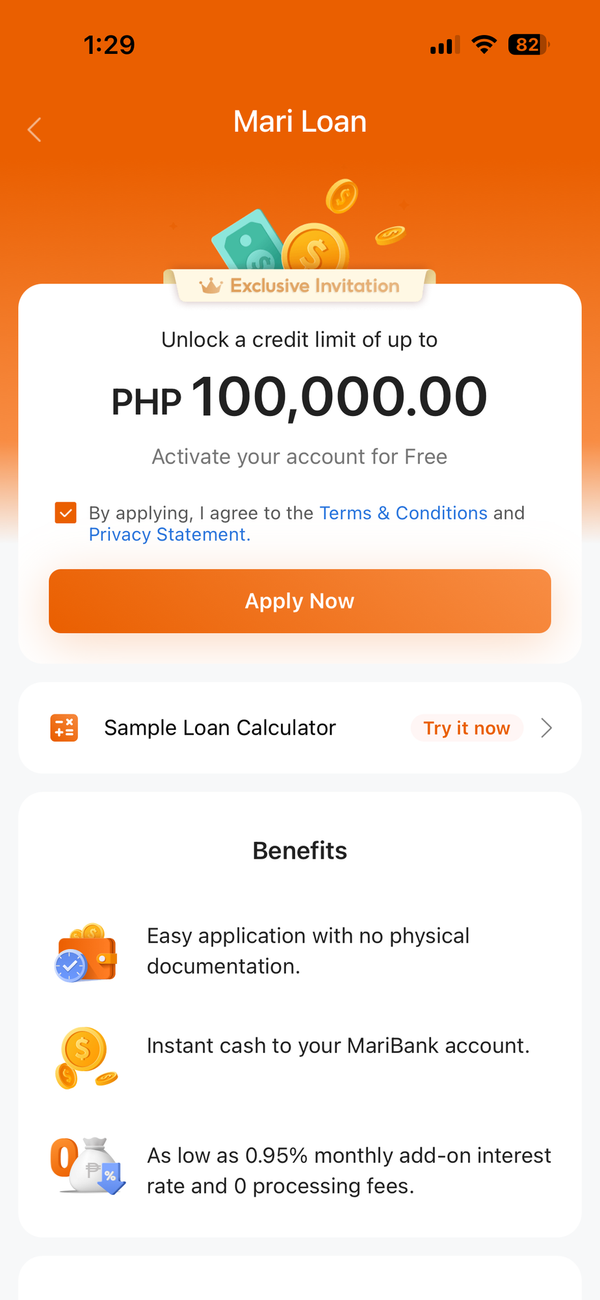
Mari Loan's entry point only appears for customers MariBank has already pre-qualified, so there's no public sign-up form, it shows up inside the app for eligible users.
- Open the MariBank app and find Mari Loan. If you've been pre-qualified, it appears as a dedicated section or banner inside the app.
- Agree to the Terms & Conditions and tap "Activate Now." Activation itself is free, no documents or proof of income required.
- Submit your applicant details as prompted in the app to complete activation.
- Tap "Withdraw Now" once your credit limit is active.
- Enter your desired loan amount (any amount from ₱1,000 up to your approved limit) and choose a 3, 6, or 12-month term.
- Review and confirm the loan agreement, the exact monthly installment and total cost show before you confirm.
- Receive your funds, disbursed directly to your MariBank Savings Account, typically within seconds of confirming.
Is Mari Loan Worth It?
The strongest case for Mari Loan is convenience: no income documents, no collateral, no guarantor, and funds land in your account within seconds of confirming a withdrawal, a genuinely faster process than most traditional bank personal loans, which typically take days to process. The 0.95% starting add-on rate is also competitive against most bank personal loans in the Philippines, which commonly start around 1.25% to 1.30% monthly, see our full Personal Loan Calculator and bank comparison for reference.
The tradeoffs worth weighing: the rate range tops out at 2.95%, more than triple the lowest advertised figure, and MariBank doesn't disclose upfront which rate you'll actually get until you're approved. The prepayment fee, 3% of outstanding principal or ₱300, whichever is higher, in effect since January 15, 2025, also means paying off a loan early isn't free, worth factoring in if you're borrowing with the intent to clear the balance ahead of schedule. And because it's invite-only, you can't apply on demand the way you can with a traditional bank loan, access depends entirely on MariBank's own pre-qualification criteria, which the bank hasn't published in detail.
Recent News & Background
Mari Loan sits under MariBank Philippines, Inc., formerly known as SeaBank Philippines before rebranding to MariBank on September 8, 2025, as part of Sea Limited's broader push to unify its digital banking brands across Singapore, Indonesia, and the Philippines under the MariBank name. Sea Limited, the parent company, also owns Shopee, which is why MariBank has run joint promos with Shopee in the past. Because Mari Loan access is restricted to pre-qualified users rather than open to the public, there isn't yet a large body of independent reviews or Reddit threads specific to this product, most public discussion of MariBank centers on its savings account and the GCash-style MariCard rather than the loan feature specifically. Our own MariBank MariCard review and MariBank safety and legitimacy guide cover the rest of what's publicly known about the platform.
Tips Before You Apply
Borrow only what you need rather than maxing out your approved limit, since interest is charged on the full amount withdrawn for the full term regardless of whether you need all of it. If you're weighing Mari Loan against a traditional bank personal loan, run both through a calculator first, our Personal Loan Calculator Philippines guide compares BDO, BPI, UnionBank, Metrobank, and more side by side using the same add-on rate math. And always keep your MariBank Savings Account funded ahead of each due date, since the monthly installment auto-deducts, a short balance means a missed payment and the 0.17% daily late penalty kicking in immediately.
Frequently Asked Questions
Sources: MariBank's official Mari Loan product page and Product Disclosure Sheet, current as of October 2026. Rates, fees, and eligibility are set at MariBank's discretion and may change, always confirm current terms in the MariBank app before applying.
Use referral code JA775362 to get ₱150 free when you sign up for MariBank.
Open MariBank Account → View MariBank Codes →